Gold savings scheme software for jewellers, at the counter and on WhatsApp
Klaros Savings Plans runs a jeweller's gold savings scheme in India. The customer accepts a Key Facts Statement in their own figures before the first payment, saves in rupees or in grams of 22K or 24K gold, asks for their balance on WhatsApp, and closes the plan as jewellery by day 364. Your team takes every payment at the counter, and you see what the scheme owes in one book.
In pilot since October 2026. Savings Plans is not in the extension catalogue yet: it is switched on with you, after going through your scheme's terms together, and it is priced after the pilot.
What a scheme needs, and what Klaros does
| What a scheme needs | In Klaros Savings Plans |
|---|---|
| Terms the customer understands | A Key Facts Statement worked out in the customer's own figures, accepted before any payment is taken. A nominee is recorded at enrolment. |
| Payments a person confirms | Money moves at the counter, where a person on your team confirms the amount. Each payment gets a receipt on WhatsApp. |
| Rupees or grams | Rupee plans, or gram plans in 22K or 24K, each bought at that purity's rate on your board. A plan can save towards a 10 g 24K coin, and you are told to have it ready when it is reached. |
| Closing within the year | Each payment becomes jewellery or a coin within 365 days, oldest first. A plan closes by day 364, and what is unused is billed as goods and held. No cash is paid back. |
| The reward | A discount on jewellery in rupees, at most 12% a year for on-time payers. Lateness lowers the rate from that day on and never takes back what was earned. |
| The bill | The piece is priced from the same tag as any walk-in sale. The making charge is shown in rupees and in grams of the piece's gold, and the discount comes off before GST. |
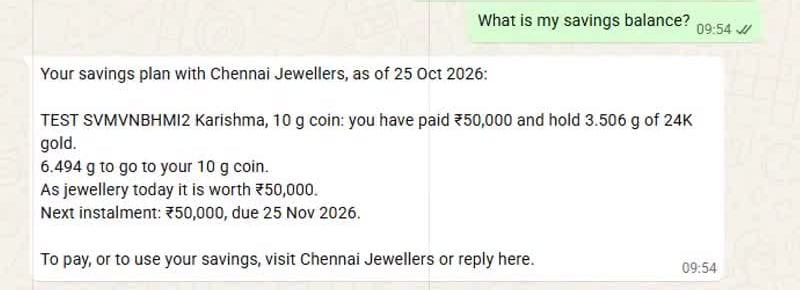
| The customer on WhatsApp | Balance, a closing quote and "skip this month", answered only to the number that holds the plan. Reminders and receipts go as WhatsApp templates, sent to Meta for approval on their own. |
| The owner's book | Advances by age, grams owed per purity, goods held for customers, and collections against your net worth if you enter it. |
| KYC and cash limits | ID seen before a jewellery or coin sale above ₹2 lakh; only the fact it was seen is kept, never the number. You are told as one customer's cash nears ₹10 lakh in a year. |
| Your auditor | A download of every plan and payment with no names or phone numbers in it. |
Why every plan closes by day 364
Under the Companies (Acceptance of Deposits) Rules, 2014, an advance received against goods is not treated as a deposit when the goods are supplied within 365 days. So Klaros gives every payment its own clock, uses the oldest payments first when a customer buys, reminds the customer before the window closes, and on day 364 bills what is left as goods held for them. No cash is paid back.
Whether that rule covers your shop depends on its legal form, and the Banning of Unregulated Deposit Schemes Act, 2019 may also apply. Those are questions for your own counsel. Klaros does not tell you a scheme is lawful: your scheme's terms, and their legal standing, stay your decision.
For the owner: what the scheme money really is
Scheme collections fund stock and the shop's running costs, so the owner's book shows them as what they are: advances you owe as goods. It lists them by age, the grams you owe in each purity, goods already held for customers, and, if you enter your net worth, collections against it. The auditor's download carries every plan and payment with no names or phone numbers.
What it does not do yet
- No UPI AutoPay. Instalments are taken at the counter, where a person confirms each amount.
- No transfer of a plan to a family member inside Klaros yet. A nominee is recorded at enrolment.
- Not a catalogue extension yet. It is switched on with you during the pilot.
- Not your billing software. GST invoices, old-gold exchange and your books stay where they are.
A film of one plan run end to end, from Key Facts to the 10 g coin, is on the jewellers page. It was recorded under the shop's first terms, and the note above the player says what has changed since.
What is gold savings scheme software?
Software that runs a jeweller's monthly gold scheme: who enrolled and on what terms, each instalment and the gold it bought, what is due next, what the customer would get today, and what the scheme owes in total. Klaros Savings Plans does this at the counter and answers the customer on WhatsApp from the same record.
Can customers save in grams of gold instead of rupees?
Yes. A plan saves in rupees, or in grams of 22K or 24K gold, each bought at that purity's rate on your board on the day it is paid. A payment taken before the day's rate is set waits for the rate. A plan can also save towards a whole 10 g 24K coin.
What happens at the end of the year?
Every payment is turned into jewellery or a coin within 365 days of being received, oldest payments first, and a plan closes by day 364. Nothing is paid back in cash: what is unused is billed as goods and held for the customer. The customer is reminded on WhatsApp before the window closes.
How is the customer rewarded for saving?
With a discount on jewellery, shown in rupees, of at most 12% a year for a customer who pays every instalment on time. A late or missed instalment lowers the rate from that day on; nothing already earned is taken back. The discount comes off the bill before GST.
Can a customer check their balance on WhatsApp?
Yes. "How much have I saved?" is answered from the customer's own account, and only to the number that holds the plan: what is paid and held, what is due next, and what it is worth as jewellery today. "What would I get if I closed it?" is answered too, and "skip this month" is confirmed with a Yes or No tap.
Does using Klaros make my scheme legal?
No software can. Under the Companies (Acceptance of Deposits) Rules, 2014, an advance against goods is not treated as a deposit when the goods are supplied within 365 days, which is why Klaros closes every payment by then. Whether that covers your shop depends on its legal form, and the Banning of Unregulated Deposit Schemes Act, 2019 may also apply. Those are questions for your own counsel, and your scheme's terms stay your decision.
What does it cost?
Savings Plans is in pilot and is priced after it. It is not in the extension catalogue yet: it is switched on with you, after going through your scheme's terms together. It sits beside Klaros for Jewellers, which is ₹4,999 a month per showroom, billed annually.
Running a scheme today in a register or a spreadsheet? Talk to us and we will go through your terms with you. See the full Klaros for jewellers page and the jewellery buyer's guide.